

The Federal Government has proposed increasing the maximum mortgage loan available through the Federal Mortgage Bank of Nigeria (FMBN) from ₦50 million to ₦85 million, while targeting 5,000 mortgages annually by 2028.
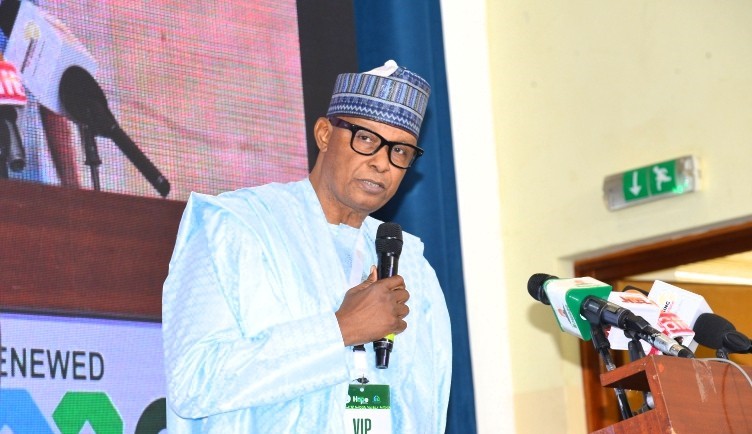
Minister of Housing and Urban Development, Muttaqha Rabe Darma, announced the measures as part of efforts to expand access to housing finance and make homeownership more accessible to Nigerians.
BusinessDay reported on July 24, 2026, that Darma had directed FMBN to increase mortgage delivery and channel a larger share of National Housing Fund (NHF) contributions into mortgage financing. The minister subsequently outlined the 5,000-mortgage annual target at the 15th Meeting of the National Council on Lands, Housing and Urban Development in Sokoto, according to a Federal Ministry of Information and National Orientation statement published on October 15, 2026.
The government’s target is to increase annual mortgage delivery from 2,000 in 2026 to 5,000 by 2028.
Under the proposed reforms, FMBN is expected to channel at least 70% of the previous year’s NHF contributions into mortgage loans annually. The government also plans to allocate between 30% and 40% of mortgage bookings to informal-sector workers, many of whom face difficulties accessing conventional housing finance because of irregular incomes.
The reforms are intended to improve access to mortgages for workers who contribute to the NHF but struggle to meet the requirements of traditional lenders.
The government also plans to establish a National Housing Finance Authority to improve coordination and regulation of the housing finance sector. Another proposal would allow eligible NHF contributors to use up to 25% of their Retirement Savings Account balances as equity contributions towards homeownership.
The proposed increase comes as FMBN records higher NHF collections.
Nairametrics reported on February 19, 2026, that the bank collected ₦152.4 billion in NHF contributions in 2025, up 48% from ₦103 billion in 2024.
The report, citing FMBN Managing Director Shehu Usman Osidi, said the 2025 collection was the highest in the scheme’s history at the time.
However, higher collections alone do not guarantee that more Nigerians will obtain mortgages. The government’s targets will also depend on the bank’s lending capacity, loan processing, eligibility requirements and the affordability of available houses.
The existing ₦50 million mortgage ceiling replaced the previous ₦15 million limit in 2022, according to earlier industry reports. The proposed ₦85 million ceiling would therefore represent a further increase in the maximum amount available to eligible borrowers.
The government has not published full implementation details for the revised ceiling, including whether all existing mortgage terms will remain unchanged.
The housing ministry is also developing a regulatory framework for the built environment, including measures to strengthen oversight of property developers and protect buyers’ funds.
The proposals come amid Nigeria’s substantial housing shortage. Estimates of the deficit vary by source and methodology, making it important to distinguish between projections and officially established figures.
The success of the mortgage reforms will ultimately depend on whether the higher loan ceiling translates into more affordable financing, more completed homes and greater access for low- and middle-income earners.