
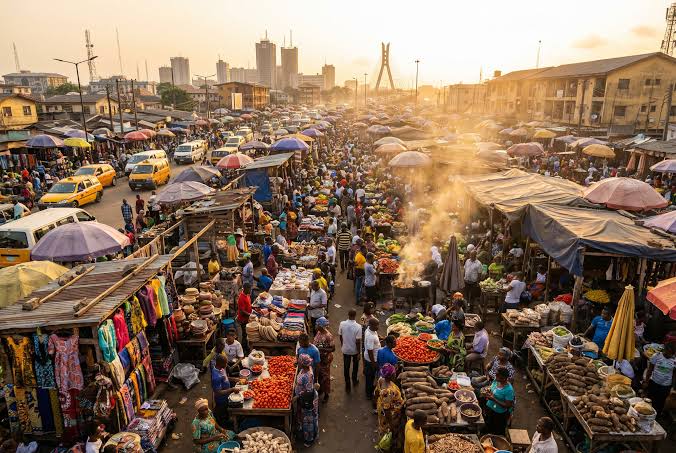

The Central Bank of Nigeria’s decision to cut its benchmark interest rate by 350 basis points may change conditions in the formal money market, but for many market traders, POS agents and other small borrowers, cheaper credit is unlikely to arrive immediately.
At its 307th Monetary Policy Committee meeting held on September 21 and 22, 2026, the CBN reset the Monetary Policy Rate from 26.5% to 23%. The bank also recalibrated its standing facilities corridor and retained the Cash Reserve Requirement for deposit money banks at 45%, according to the CBN’s September 22, 2026 monetary policy decision.
For a trader borrowing from a cooperative society, a POS operator taking working-capital financing or a micro-business using a microfinance bank, the final cost of credit can depend on the lender’s funding costs, operating expenses, repayment risks and pricing structure.
That is why the 350-basis-point reduction may initially feel distant from the street.
The CBN itself said on September 22, 2026 that the move was an operational reset designed to address a disconnect between the official MPR and rates actually prevailing in financial markets. Nairametrics reported the same day that the apex bank said the MPR had stood at 26.5% while the interbank and Standing Deposit Facility rates were around 22%, making the MPR the “de jure” rate while the SDF effectively operated as the “de facto” rate.
That distinction matters for small borrowers because a lower benchmark does not automatically rewrite the pricing of every loan product.
The transmission from monetary policy to lending rates can be slow and uneven even within the formal banking system.
TheCable reported on June 11, 2026 that Access Holdings Chief Executive Officer Innocent Ike explained that banks cannot simply reduce lending rates immediately after an MPR change because their own funding costs include existing deposit contracts and other obligations.
The same report cited the International Monetary Fund’s June 2026 Article IV assessment of Nigeria, which found that lending rates respond more strongly to MPR increases than to reductions. According to the IMF analysis reported by TheCable, a 100-basis-point increase in the policy rate typically pushes lending rates up by about 175 to 180 basis points, while a similar reduction produces only a 25 to 30-basis-point decline.
For informal and semi-formal borrowers, the connection can be even weaker.
A cooperative society may set its lending rate based largely on members’ contributions, administrative costs and decisions taken within the cooperative. A POS operator using short-term financing may instead face fees determined by the lender’s assessment of repayment risk, transaction activity and the cost of collecting repayments.
Microfinance banks are more closely connected to the formal financial system, but their lending costs also reflect the economics of serving small borrowers. Small loan sizes, operating expenses and credit risk can keep borrowing costs high even when the broader monetary environment begins to ease.
The CBN’s September 2026 decision came as several headline economic indicators improved.
The CBN said inflation had moderated to 15.39% in August 2026 and pointed to improving economic activity and macroeconomic conditions as part of the basis for recalibrating its monetary-policy framework. The September 22, 2026 decision also retained the 45% CRR for deposit money banks.
Those developments can improve the environment in which banks and other financial institutions operate. But they do not guarantee that a trader seeking ₦200,000 to restock, or a POS agent needing additional working capital, will immediately receive a cheaper loan.
For those borrowers, the relevant number is not simply the MPR announced by the CBN. It is the interest rate, fee or repayment amount attached to the credit they can actually access.
The September 22, 2026 decision could therefore become important for small borrowers if lower funding costs eventually move through banks and other lending institutions. But that is a transmission process, not an automatic consequence of the headline rate cut.
For now, the CBN has changed the benchmark. The question for the market woman, POS agent and micro-borrower is when, and by how much, their own borrowing costs will follow.